A Claim Is Only As GoodAs Its Documentation.
We document the loss as the work happens, build the scope your adjuster expects, and bill the carrier directly where your policy allows — so the claim reflects the real cost of the damage.
Call 888-838-7170Contact usXactimatethe platform carriers useDirect billingwhere policy allows60 minon site, 24/74.8★179 reviews
Call Us First. Then Open The Claim.
You choose your restorer — a carrier cannot require a specific vendor. What affects the outcome is the quality of the record behind the claim.
The first hour decides how big the loss gets. Paperwork can start while trucks are already moving.
When water or fire hits, the instinct is to call the insurance company first. The problem is that a claim takes time to open and damage does not wait — water keeps migrating into assemblies, and under published industry guidance mold can begin on damp materials within roughly 24 to 48 hours.
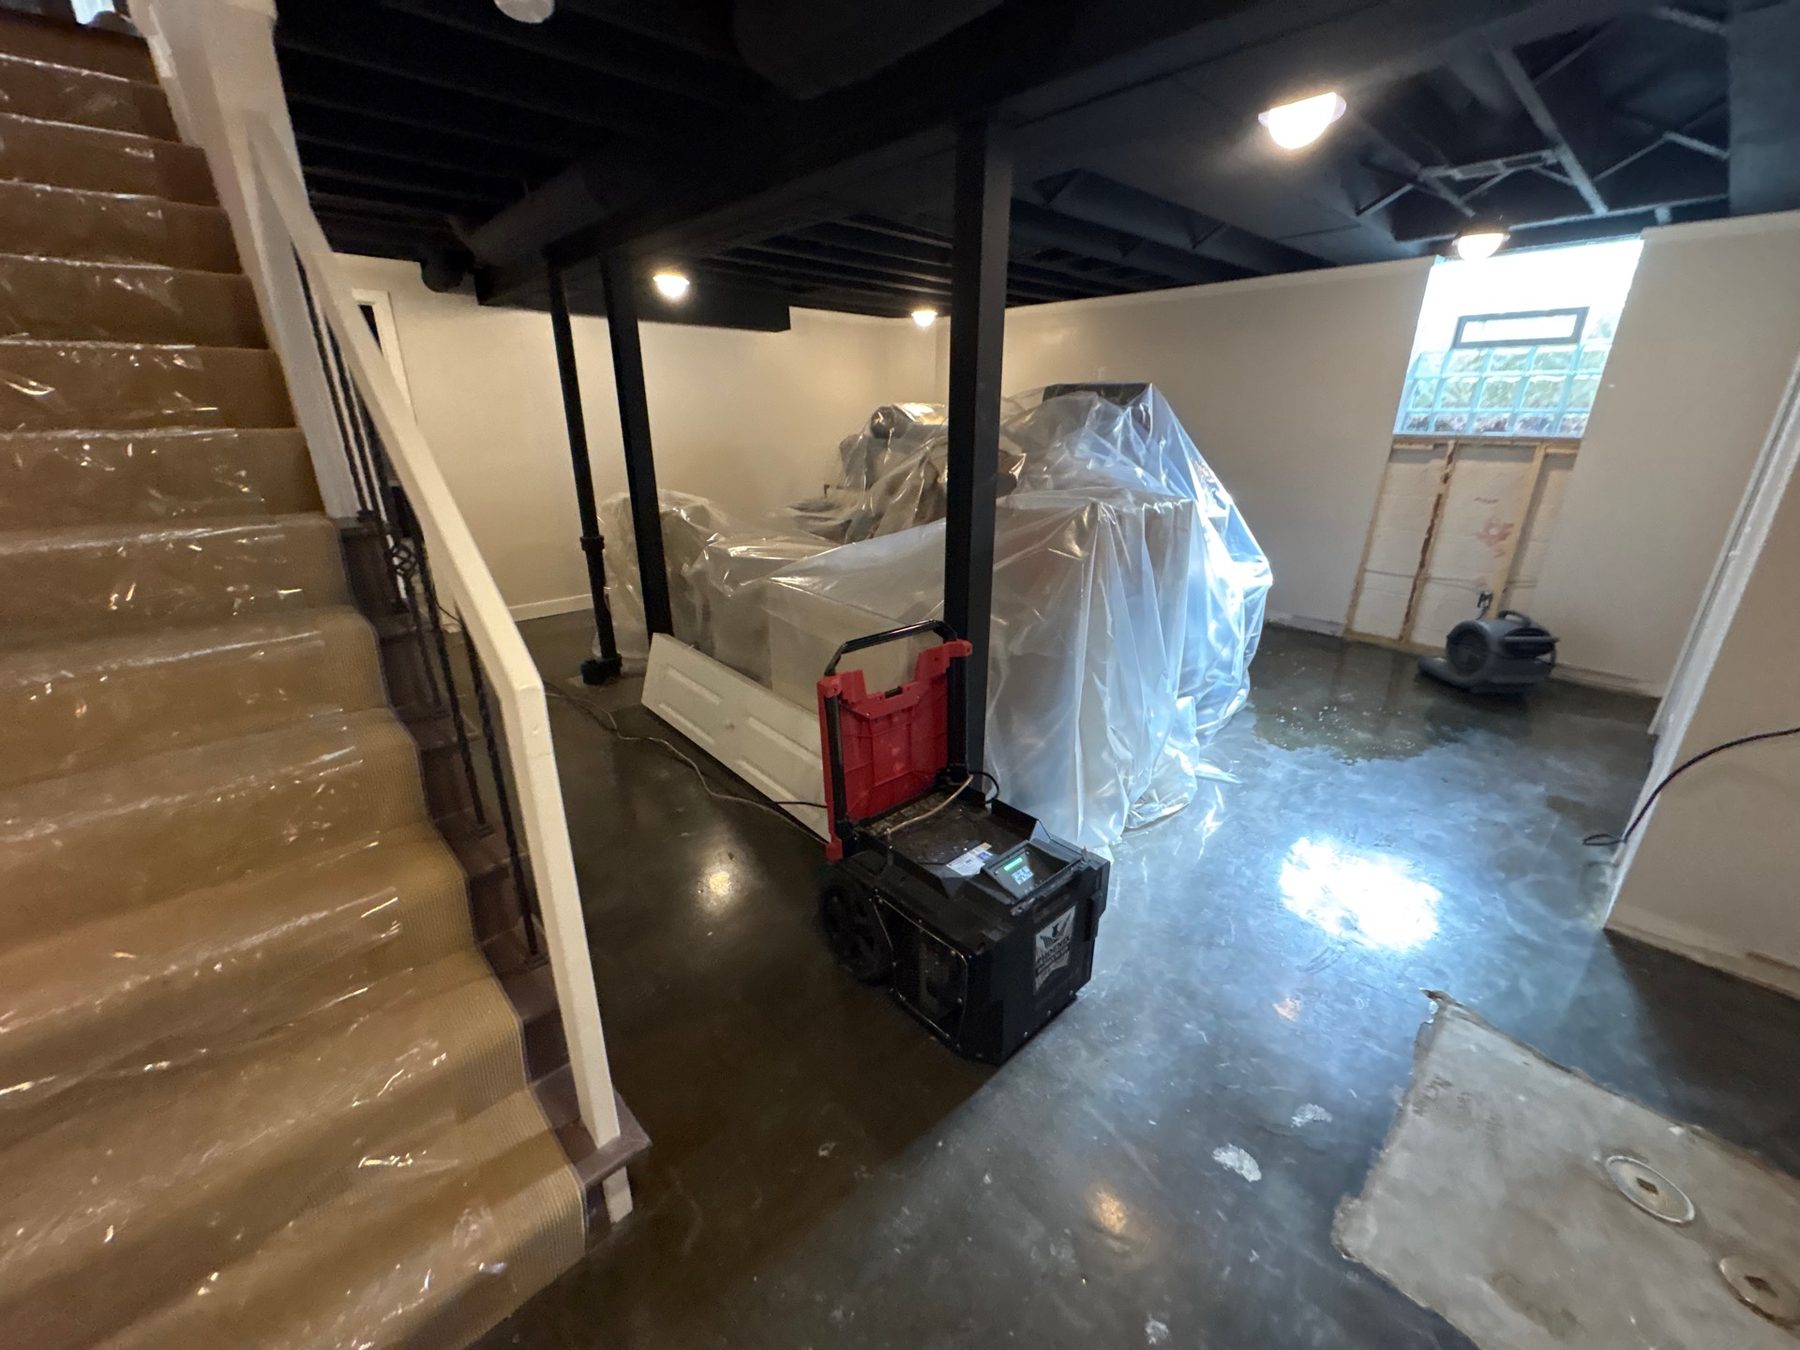
Calling us first means a certified crew is stopping the damage while the claim is being opened, and it means the loss is documented from the moment we arrive — measured areas and photographs taken before drying equipment changes what the site looks like. Reconstructing that afterwards is where scope disputes come from.
The Record Behind Your Claim.
Four things an adjuster needs, produced as the job runs rather than assembled at the end.
The same documentation package goes to every carrier, because the standard does not change with the logo on the letterhead.
What To Do In The First Hour.
The order matters more than people expect.
- Step 01Make sure everyone is safeSafety first. Keep clear of standing water near outlets, and do not re-enter a fire-damaged structure until the fire department has cleared it.
- Step 02Call DriForceA person answers 24/7 and dispatches a certified crew immediately. Acting fast is what prevents a mitigation job becoming a rebuild.
- Step 03We document while we stabilizeSource control and containment first, with measured areas and photographs taken before equipment is placed.
- Step 04We help you open the claimWe work with you to document the damage and communicate with your carrier, including the paperwork the claim needs.
- Step 05We build the scope and bill the carrierLine items written to the scope actually performed, billed directly where your policy allows.
What We Do That You Should Not Have To.
A well-handled claim is the single biggest thing that makes restoration affordable.
- 01We meet the adjuster on siteWalking the loss together removes most of the disagreements that otherwise surface weeks later in writing.
- 02Measured, not estimatedRoom-by-room dimensions and the extent of migration, including where water crossed into shared assemblies — the usual origin of scope disputes.
- 03Drying goals, logged dailyTarget values set from the materials involved and readings logged to completion, so stopping drying is evidenced rather than asserted.
- 04Supplements raised when foundHidden damage and code-required upgrades submitted with the reading or photograph that prompted them, at the time.
- 05One file through the rebuildMichigan Builder License #2102202262 keeps mitigation and reconstruction on one claim, rather than two vendors and two scopes.
- 06You are not financing itDirect carrier billing where your policy allows, so the claim does not become your cash-flow problem.
Insurance & Claims Guides.
Coverage, documentation and the decisions that determine whether a claim closes cleanly.
What We Need From You (And What We Do Not).
Short list, and shorter than people expect.
Claims, Answered.
Should I call you or my insurance company first?
Call us first. We provide 24/7 emergency response and will dispatch a crew immediately — acting fast prevents further damage, and the documentation we gather on arrival is what the claim is built from. You can open the claim while we are already working.
Do you work with my carrier?
We have worked with every major carrier and document in Xactimate, the estimating platform most of them use. That is what keeps a claim moving instead of bouncing back for more information.
Who deals with the adjuster?
We do, alongside you. We meet the adjuster on site where that helps, walk the loss, and provide the measured areas, moisture logs and photo index behind every line item.
What if the carrier misses something?
Hidden damage and code-required upgrades get documented and submitted as a supplement with the reading or photograph that prompted them — not asserted after the fact.
Does using you affect my claim?
You choose your restorer; your carrier cannot require a specific vendor. What affects a claim is the quality of the documentation behind it.
What does it cost me?
For most covered losses your deductible is your share and we bill the rest to the carrier where your policy allows. See financing and insurance for the three ways restoration gets paid for.
Who Is Writing Your Documentation.
The documentation is only as credible as the firm producing it.
- 01IICRC Certified FirmWater restoration, applied structural drying, microbial remediation, fire and smoke, odor control and trauma certifications held on staff, listed publicly in the IICRC Global Locator under Absolute Water Removal, LLC dba DriForce Property Restoration.
- 02Michigan Builder License #2102202262Mitigation and reconstruction on one license and one contract, so the loss does not stall between the drying finishing and the rebuild starting.
- 03One-year workmanship warrantyOn reconstruction we perform, separate from any manufacturer warranty on materials.
- 04Xactimate and DASHWe estimate in the platform your carrier already uses and run job management on one record, so the estimate and the evidence match.
Tell us what happened. We will document it properly.
Call any time — a person answers. We stabilize the property first and build the claim from what we find, not from memory.
Oakland, Macomb and Wayne
St. Clair and the Blue Water Area
See financing and insurance for how restoration gets paid for, or the service pages for the work itself: water damage, fire and smoke damage, mold remediation, storm damage and reconstruction. Adjusters: see what we send you.
Tell us about the loss
Address and what happened is enough to start. If it is an emergency, calling is faster.
